

Here are two pieces of weekly data that I follow.
MBA: Mortgage Applications Remain Weak
From the Mortgage Bankers Association: Mortgage Applications Decrease in Latest MBA Weekly Survey
Mortgage applications decreased 1.5 percent from one week earlier, according to data from the Mortgage Bankers Association’s (MBA) Weekly Mortgage Applications Survey for the week ending September 18, 2026. Last week’s results included an adjustment for the Labor Day holiday.
The Market Composite Index, a measure of mortgage loan application volume, decreased 1.5 percent on a seasonally adjusted basis from one week earlier. On an unadjusted basis, the Index increased 9 percent compared with the previous week. The Refinance Index decreased 3 percent from the previous week and was 62 percent lower than the same week one year ago. The seasonally adjusted Purchase Index decreased 1 percent from one week earlier. The unadjusted Purchase Index increased 9 percent compared with the previous week and was 11 percent lower than the same week one year ago.
“Mortgage rates vaulted higher last week, with the 30-year fixed rate at 7.12 percent – the highest level since May 2024. With fixed rates much higher, more borrowers opted for ARMs, with the ARM share reaching 9.8 percent, as rates for 5/1 ARMs were more than a percentage point lower than those for fixed rate loans,” said Mike Fratantoni, MBA’s SVP and Chief Economist. “Applications for both refinance and purchase loans declined further last week, noting that the comparison is to the week that included the Labor Day holiday. With this week’s decline, the pace of refinancing fell to its slowest pace since February 2025.” emphasis added
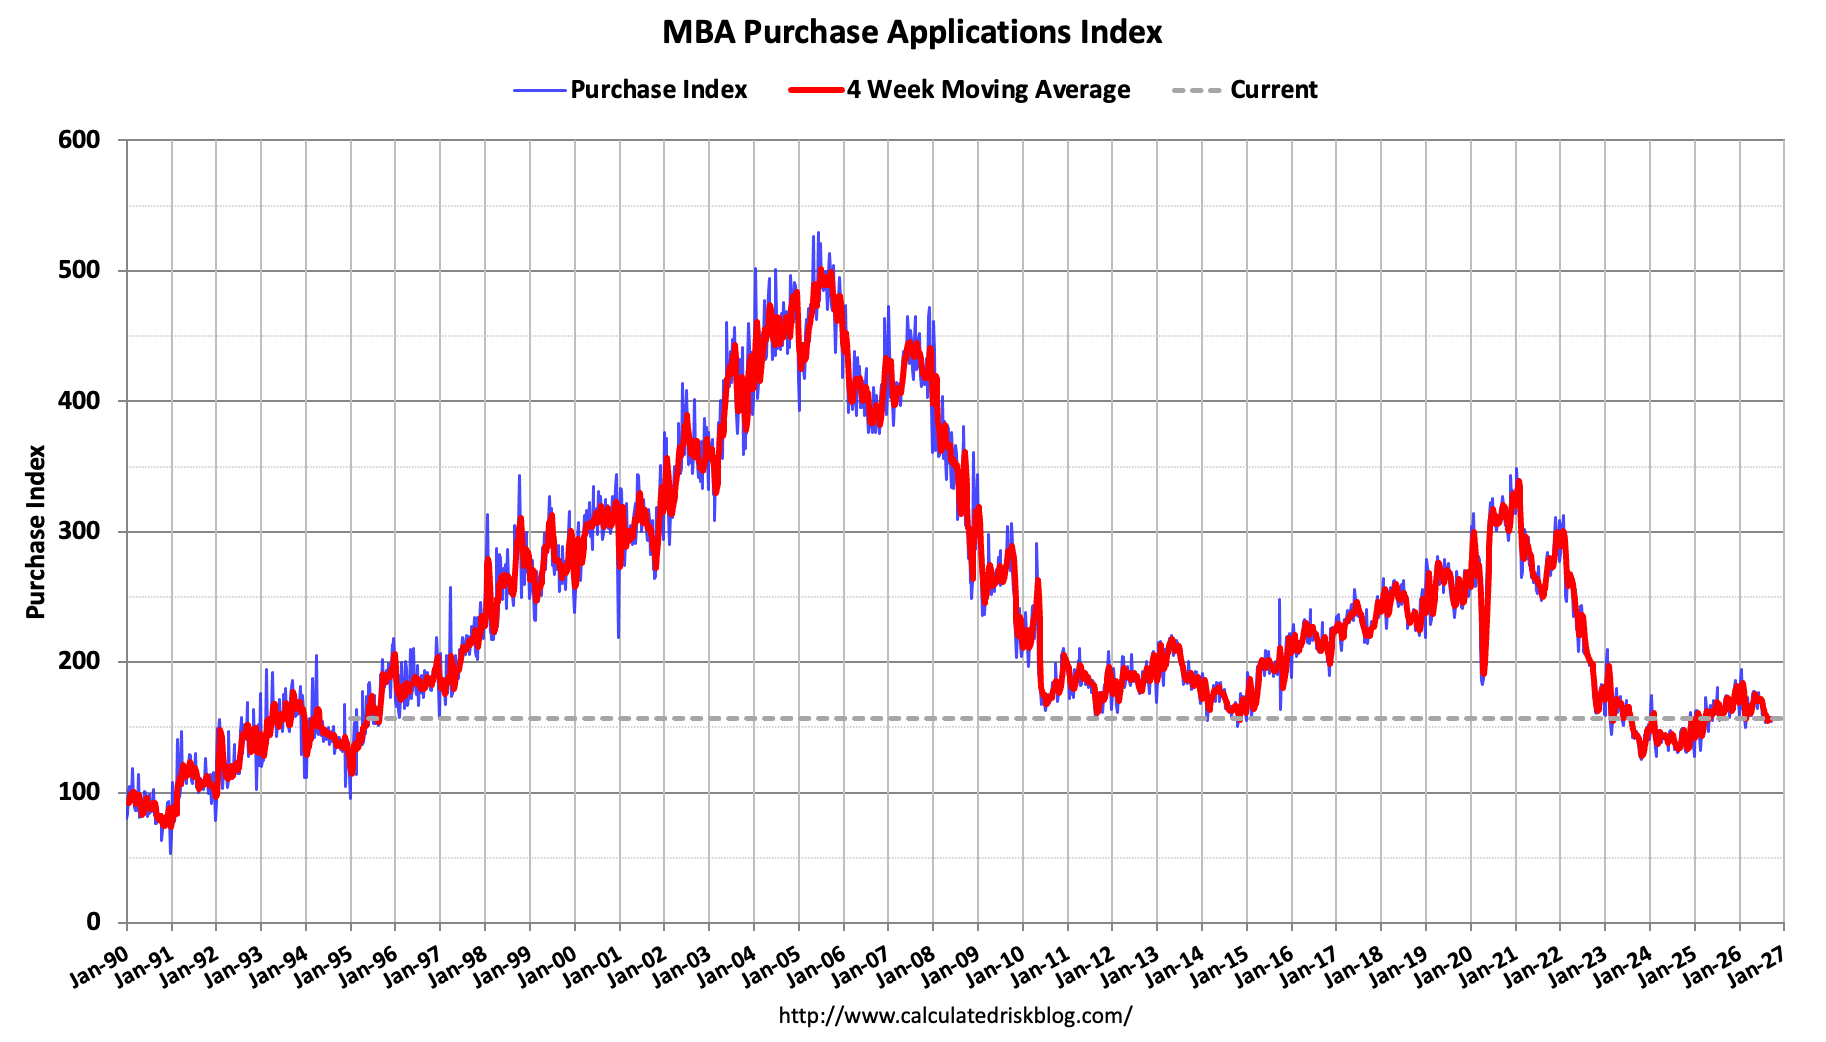
This graph shows the seasonally adjusted MBA mortgage purchase index. According to the MBA, purchase activity is down year-over-year unadjusted.
Red is a four-week average (blue is weekly). Purchase application activity remains depressed.
The second graph shows the refinance index since 1990.
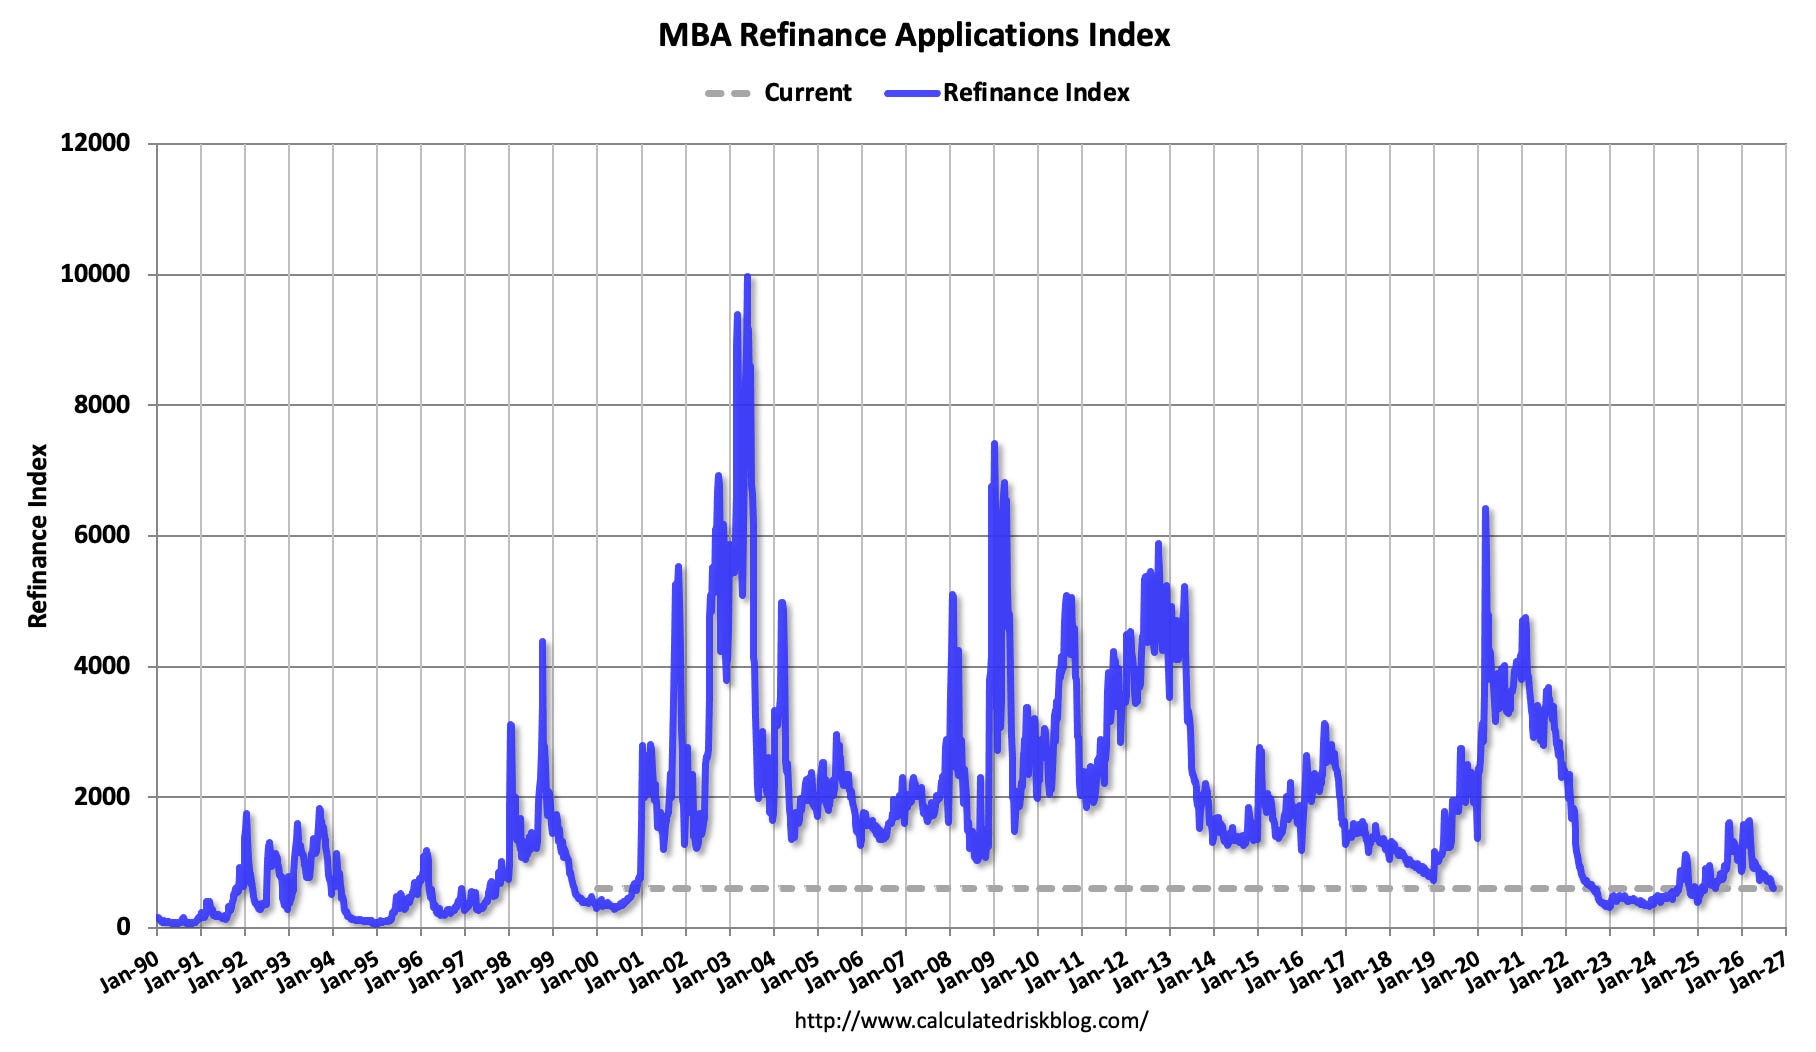
The refinance index is historically very low and has declined recently with the increase in mortgage rates.
Inventory Up Year-over-year
And here is some timely data from Altos Research on active single-family inventory. This graph shows the seasonal pattern for active single-family inventory since 2015 through last Friday (September 18th).
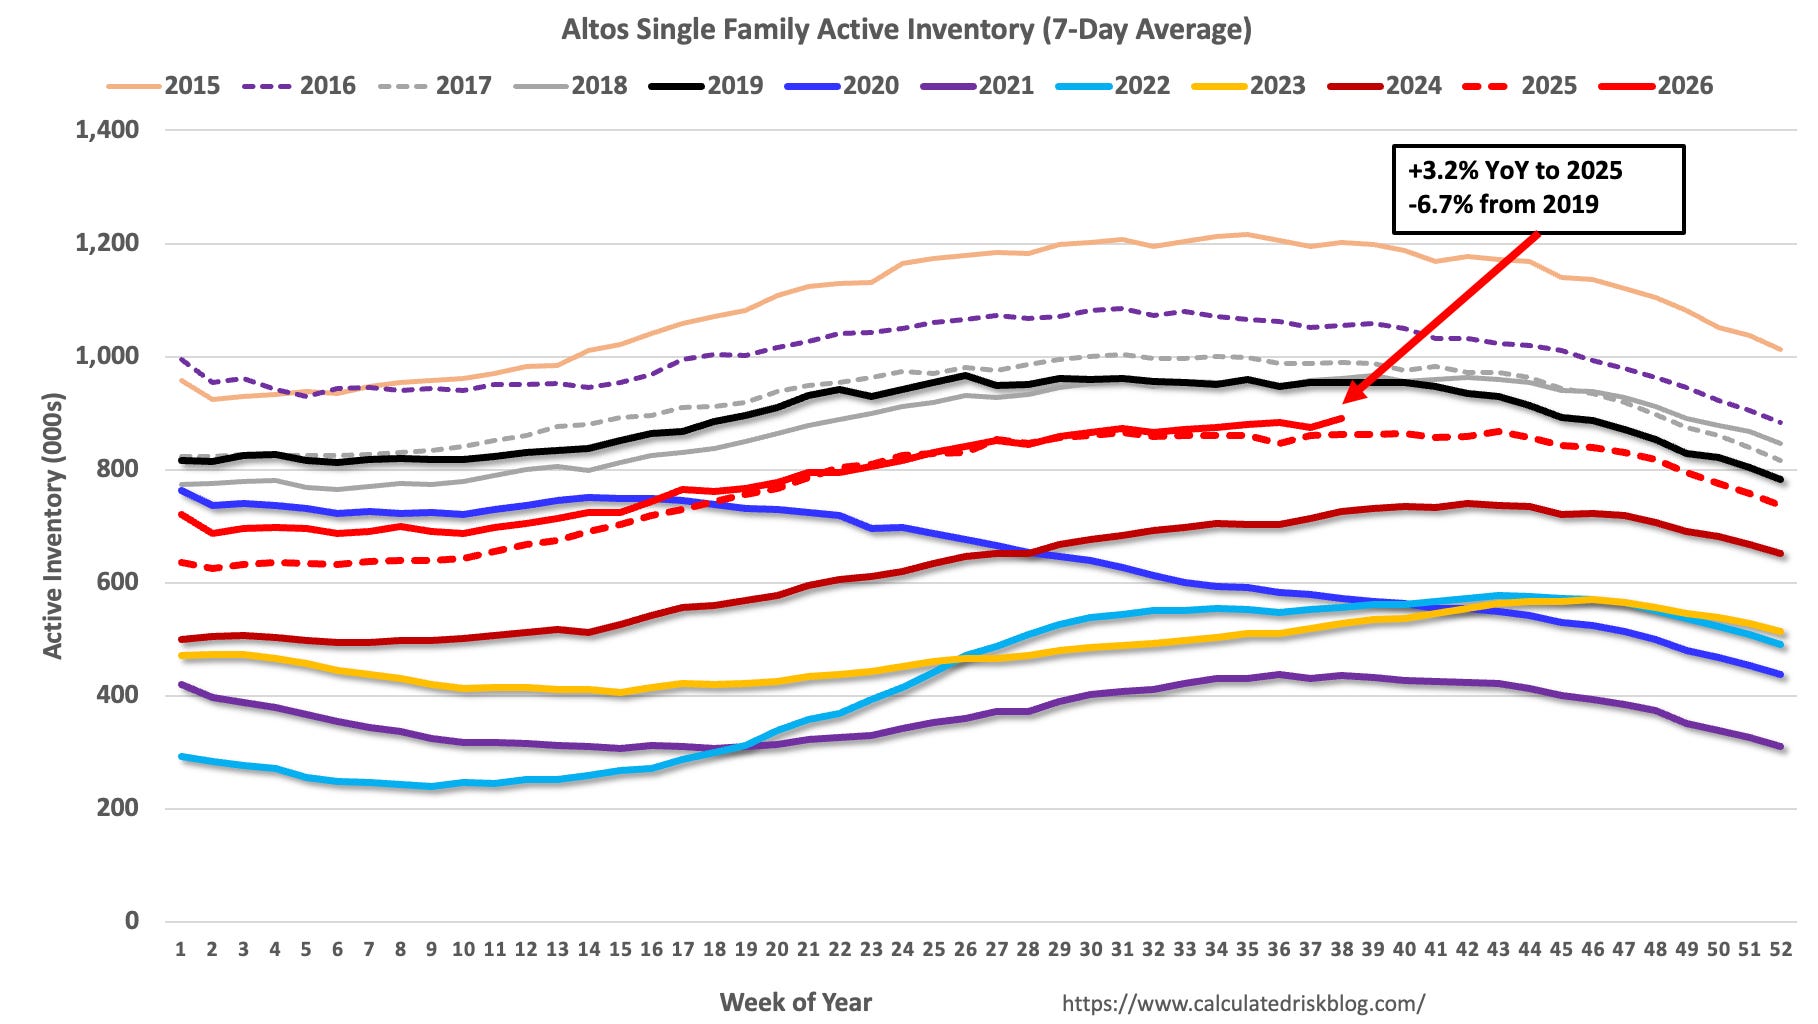
The red line is for 2026. The black line is for 2019.
Inventory was up 3.2% compared to the same week in 2025 (the previous week it was up 1.5%), and down 6.7% compared to the same week in 2019 (last week it was down 8.5%).
This slowdown in inventory growth has been a key story in 2026, however, it appears inventory is picking up a little with higher mortgage rates.
Another metric that Altos reports is the median list price. This graph from Altos shows the median list price since 2021. The 7-day median list price is down 1% year-over-year.
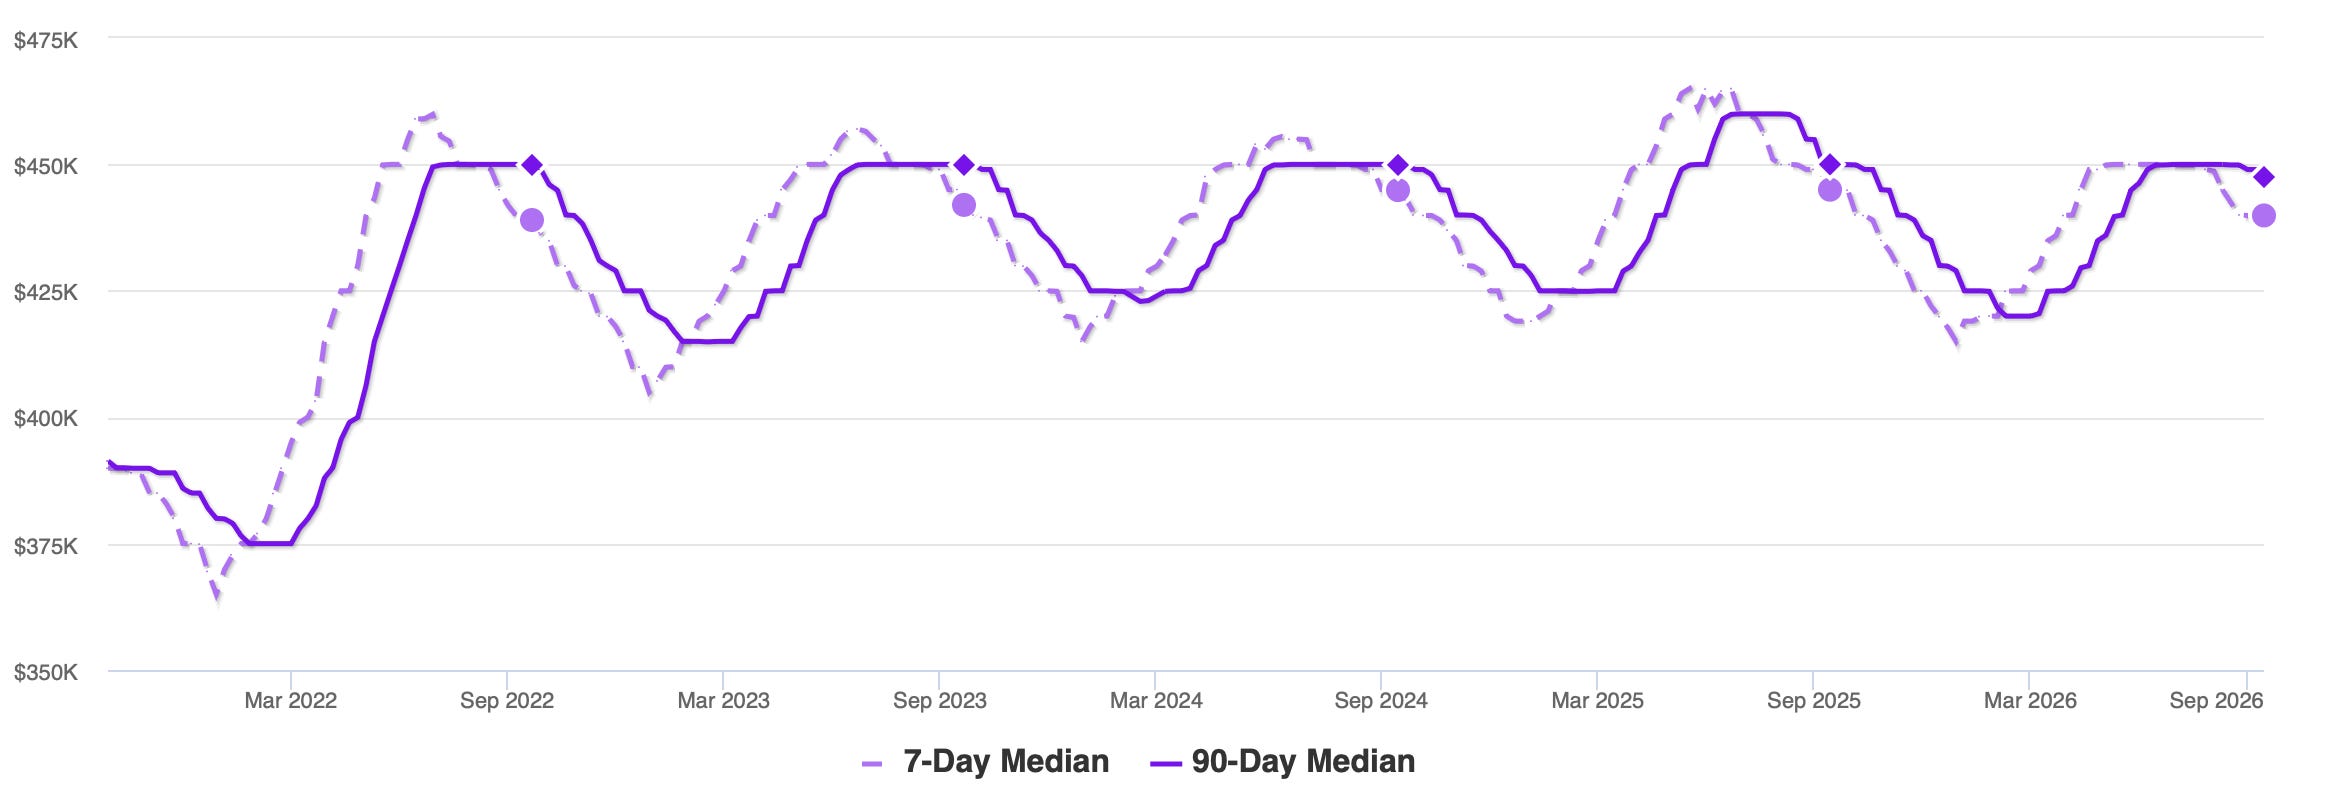
The median list price has been mostly unchanged for the last 4 years (other than the usual seasonal swings)!
Inventory has picked up slightly and demand is weak. With 30-year mortgage rates above 7%, existing home sales will likely slow and house prices will be under pressure.